Pet Insurance Claims & Coverage: Compare Plans With AI
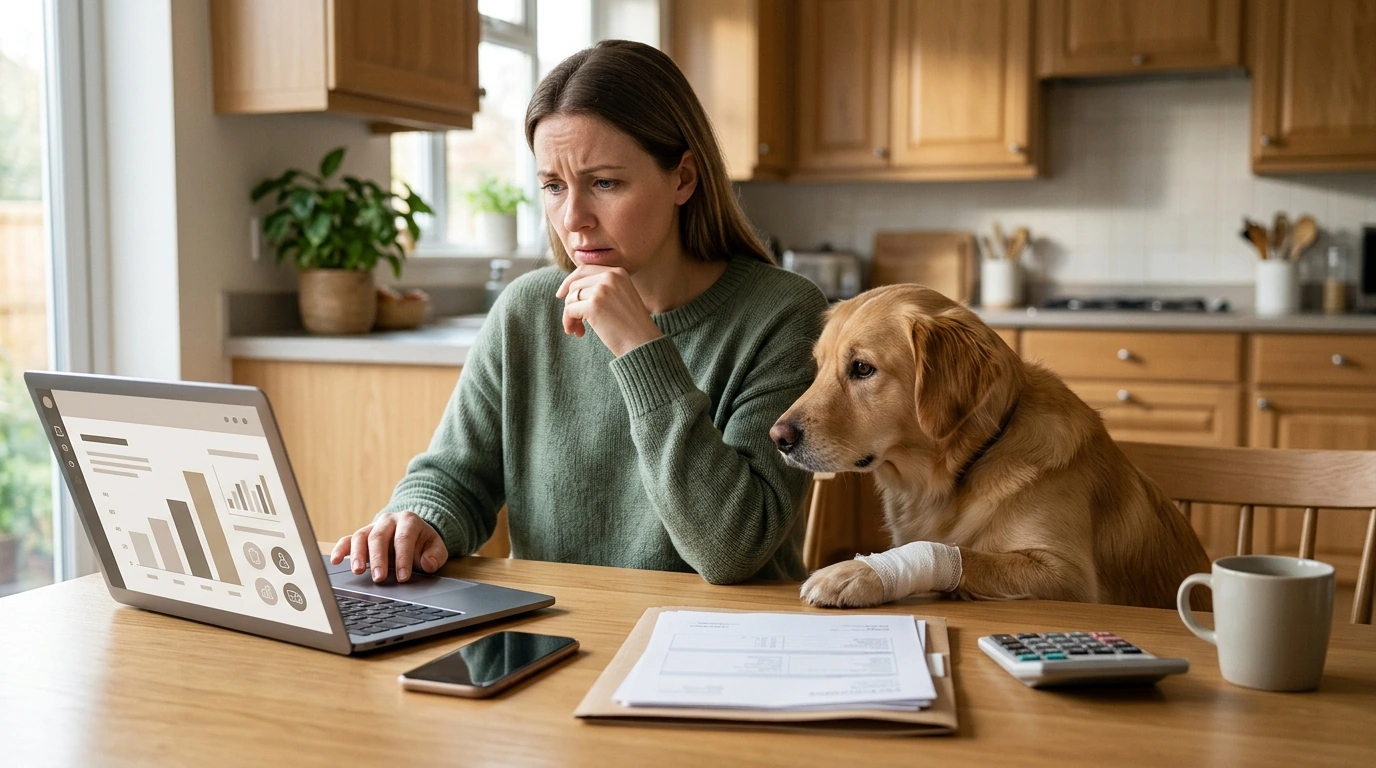
Pet insurance can turn a stressful emergency into a manageable plan—if the policy fits your pet and the claim is filed cleanly. The tricky part is that most plans look similar at a glance, but small details (deductible type, waiting periods, exclusions, and payout limits) can change your real out-of-pocket cost. Below is a practical breakdown of how pet insurance works, what’s commonly covered, how to avoid claim slowdowns, and how AI-style comparison tools can help you make smarter choices. For more guidance, see Pet Insurance: It Could Save Your Pet’s Life, Could Save You Money.
How pet insurance works in real life
Most pet insurance policies work on a reimbursement model: you pay the vet bill at checkout, submit a claim, and then receive reimbursement based on your plan’s rules. That means your financial “worst case” depends not only on the premium, but also on how much cash you might need available the day of treatment. For further reading, see Best Pet Insurance Companies of 2026 – Consumer Reports.
Three variables do most of the heavy lifting in determining reimbursement:
- Deductible: Often annual, sometimes per-condition. This is the amount you pay before reimbursement begins.
- Reimbursement percentage: Commonly 70%–90% of eligible costs after the deductible.
- Payout limits: Annual limits are common; some plans also use lifetime limits or per-incident caps.
Waiting periods can apply to accidents, illnesses, and especially orthopedic conditions. Pre-existing conditions are typically excluded, so your pet’s medical history matters. For a high-level consumer overview, it can help to review guidance from sources like the NAIC pet insurance consumer resource and the American Veterinary Medical Association’s pet insurance page.
Coverage types and common add-ons
Most plans fall into two main categories, plus optional add-ons:
- Accident-only: Focuses on injuries such as fractures, bites, lacerations, or foreign body ingestion. Premiums are usually lower.
- Accident and illness: Adds coverage for infections, chronic conditions, cancer, allergies, and other medical issues beyond injuries.
- Wellness/preventive add-ons: May help with routine exams, vaccines, dental cleanings, and parasite prevention (benefits vary widely).
When comparing plans, watch for optional benefits that can swing your yearly costs: exam fees, prescription diets, rehab/physical therapy, behavioral therapy, and dental illness coverage.
Typical coverage overview (varies by provider and plan)
| Item | Often covered with accident/illness | Often excluded or limited | Notes to verify |
|---|---|---|---|
| Emergency surgery | Yes | N/A | Confirm payout limits and whether exam fees count |
| Diagnostics (X-ray, ultrasound, labs) | Yes | N/A | Check if pre-authorization is required for big procedures |
| Chronic conditions (e.g., allergies, diabetes) | Usually | Pre-existing conditions | Ask how “curable” conditions are handled after symptom-free periods |
| Dental disease | Sometimes | Often limited | Many plans require proof of annual dental care |
| Wellness visits and vaccines | Only with add-on | Often excluded on base plans | Compare annual caps vs. premium increase |
The claim process: from invoice to reimbursement
A smooth claim is mostly about documentation consistency. Before leaving the clinic, ask for:
- An itemized invoice (line items and prices, not just a total)
- The visit’s medical notes/SOAP notes
- Diagnostic results (lab work, imaging reports) tied to that visit
Submit promptly through the insurer’s portal or app. Many policies have submission windows, and waiting too long can create avoidable friction. Then cross-check for mismatches: pet name spelling, date of service, and line items should align between the invoice and the medical record. If something is vague (“limping” vs. “suspected cruciate injury”), ask the clinic to clarify so the insurer doesn’t treat it as related to an older symptom.
Why claims get delayed or reduced
AI-driven decision tools: practical ways to compare policies
Quick scenario test to compare plans
| Scenario | Estimated vet bill | Plan lever that matters most | What to check |
|---|---|---|---|
| Foreign body ingestion surgery | $3,000–$7,000 | Annual limit + reimbursement rate | Coverage of exam fees, hospitalization, and imaging |
| Skin allergies (ongoing meds + visits) | $800–$2,500/year | Deductible type | Per-condition vs. annual deductible; chronic coverage rules |
| Knee injury (possible CCL/ACL surgery) | $3,500–$6,500 | Orthopedic exclusions | Waiting periods, bilateral condition clauses, rehab coverage |
Building a claim-ready routine
A helpful guidebook for navigating coverage and claims
If you prefer a step-by-step reference that ties coverage basics to real claim decisions and modern comparison methods, consider keeping a dedicated guide on hand: Pet Protection Made Simple: Your Ultimate Guide to Pet Insurance, Claims, and AI-Driven Decisions. It’s a practical way to connect policy language to what you actually submit, track, and verify during a claim.
For comfort during long recovery days and follow-up appointments, a supportive home setup can also matter. Some shoppers pair planning with a few quality-of-life upgrades like the Luxury High-Back Recliner Sofa Set for easier downtime or the Muscle Relaxation Toolkit for Total Tension Relief – 3-in-1 Bundle for Deep Muscle Relaxation to help manage the human side of stressful vet weeks.
FAQ
What documents are usually needed for a pet insurance claim?
Most claims require an itemized invoice and the full medical notes from the visit, plus any diagnostic results (lab work or imaging reports). Some insurers also request prior records if the condition could be considered pre-existing.
Are pre-existing conditions ever covered later?
Many insurers exclude pre-existing conditions permanently, but some consider certain issues “curable” after a defined symptom-free period. Confirm the exact definition and what documentation is required to prove that timeline.
How can AI tools help choose a pet insurance plan?
They can compare the same claim scenarios across plans, estimate out-of-pocket costs under different deductibles and reimbursement rates, and flag exclusions or annual limits that could cap major events. They’re most useful when you input realistic vet bill ranges for your location and pet’s risk factors.




Leave a comment